September 25, 2026
Sometimes the best part of our day is hearing that we were friendly, informative, and knowledgeable, because that’s exactly how we want every customer to feel at Bridgeway Insurance. Whether you’re comparing the best home insurance before fall weather shifts, or trying to lock in the best auto insurance for your daily drive, we’ll break it down in plain English and help you choose what makes sense. We also help families and property owners with condo insurance, and we guide business owners through commercial insurance so they’re not guessing when it matters most. If you run vehicles for work, we can also talk through commercial auto insurance and what it should cover for your operations. We work with customers in Hattiesburg, Bay Saint Louis, Gulfport, Huntsville, Orange Beach, Santa Rosa, Madison, Brandon, Ocean Springs, and Hoover, and we’ll treat you like a neighbor every step of the way. Send us a message today to get a quote and talk with an agent.
View Post
September 23, 2026
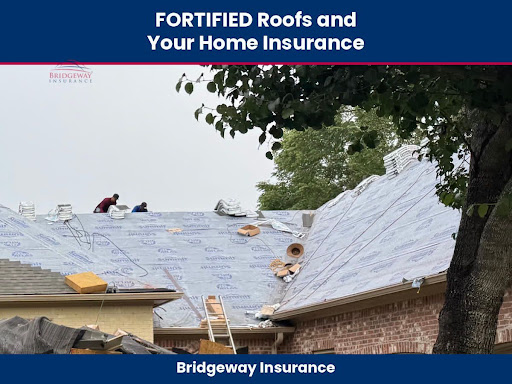
Does a FORTIFIED roof lower your home insurance? In much of the Southeast, yes. FORTIFIED is a construction standard from the Insurance Institute for Business and Home Safety: a sealed roof deck, stronger fastening, and better edges and flashing. Because those roofs hold up better in hurricanes, tornadoes and hail, carriers across our states credit them on the wind portion of a homeowners policy. Several states also fund grant programs that help cover the upgrade, and Louisiana will require insurers to apply the discount beginning January 1, 2027. One step homeowners often miss: the credit applies only once the FORTIFIED certificate is on file with the carrier. We can check your eligibility and time the paperwork to your renewal. See the state-by-state breakdown at the link.
View Post
September 23, 2026
Does a FORTIFIED roof lower your home insurance? In much of the Southeast, yes. FORTIFIED is a construction standard from the Insurance Institute for Business and Home Safety: a sealed roof deck, stronger fastening, and better edges and flashing. Because those roofs hold up better in hurricanes, tornadoes and hail, carriers across our states credit them on the wind portion of a homeowners policy. Several states also fund grant programs that help cover the upgrade, and Louisiana will require insurers to apply the discount beginning January 1, 2027. One step homeowners often miss: the credit applies only once the FORTIFIED certificate is on file with the carrier. We can check your eligibility and time the paperwork to your renewal. See the state-by-state breakdown at the link.
View Post